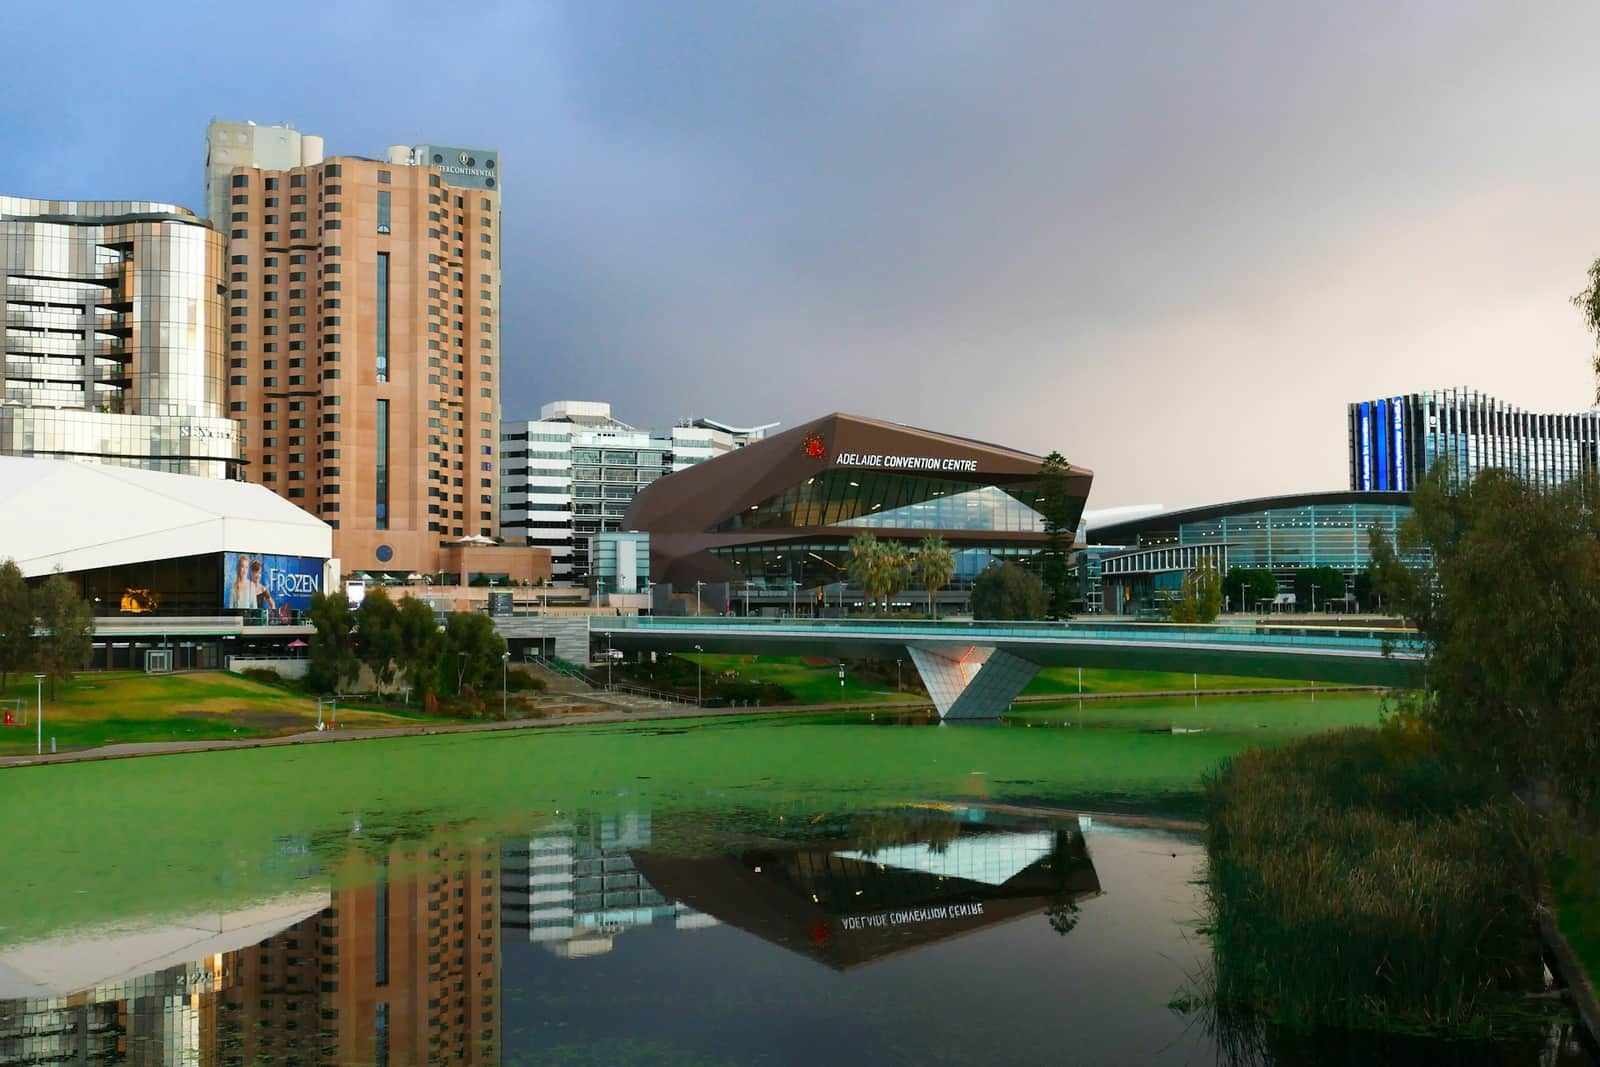
Urgent business loans in Adelaide make good use of a system that started here. South Australia introduced the Torrens title system in 1858, and today that register, now lodged electronically through Land Services SA, is one reason a property-secured loan can move quickly. We fund $20k to $250k, often on the same day, and up to $5m in 24–48 hours against SA property once documents are complete.
What’s squeezing Adelaide businesses?
Adelaide’s economy has a distinctive mix, and each part has its own cash-flow trap.
Defence and advanced manufacturing. Osborne’s naval shipyards, Edinburgh’s defence precinct and the supply chains around them are growing, with long-term submarine and shipbuilding programs ahead. Suppliers invest in staff, certifications and tooling long before they’re paid on milestones. See manufacturing funding for the pattern.
Wine and food. The Barossa, McLaren Vale, Clare Valley and Adelaide Hills pay for grapes, barrels, bottling and labels months or years before the wine is sold. Export markets reopening in recent years brought new orders, and new orders need working capital. Our agriculture page covers seasonal lending.
Health and services. Adelaide’s hospitals, research precincts and aged-care operators support a large network of clinics, labs and service contractors.
Construction. Housing growth in the northern suburbs and down the southern corridor keeps builders busy, but progress payments still lag wages and materials.
How fast is an urgent loan in Adelaide?
For a trading business needing $20k to $250k, a same-day decision and funding are possible when bank statements show steady turnover. For property-secured loans, 24–48 hours from complete documents is realistic.
Here’s what the property path looks like:
- Enquire. Sixty seconds online. No effect on your credit score.
- Talk it through. A lending specialist confirms the amount, purpose, security and exit.
- Search and value. Title search, then a desktop or full valuation.
- Sign. Loan documents signed electronically by every borrower and owner.
- Lodge and fund. Caveat or mortgage lodged electronically with Land Services SA; funds released.
That’s usually faster than a bank. If you’re weighing the two, our comparison of urgent business loans versus banks sets out the trade-offs.
How do caveats and mortgages work on SA titles?
Land Services SA operates South Australia’s land titles registry on behalf of the Registrar-General. Mortgages have been lodged electronically since 2018, and caveats and caveat removals were added to the mandate on 3 August 2020. A broader mandate from April 2024 extended electronic lodgement to most other dealings. Electronic lodgement networks such as PEXA and Sympli both operate in SA.
A caveat loan places a caveat on the title that stops other dealings being registered until the loan is repaid and the caveat is withdrawn. It doesn’t need the first mortgagee’s consent to lodge, which is why it’s often faster than a registered second mortgage.
Two SA quirks worth knowing:
- Community titles and strata. SA has both strata titles and community titles. Either can secure a loan; have your corporation’s details ready.
- Part-parcel caveats. A caveat over only part of a parcel needs a plan and is exempt from electronic lodgement, which slows things. It’s rare for a loan, but it happens with farming land.
What SA property works as security?
| Property | Typical areas | What to expect |
|---|---|---|
| House or townhouse | Norwood, Unley, Prospect, Golden Grove, Mawson Lakes | Desktop valuation often possible |
| Investment unit | Adelaide CBD, Glenelg, Henley Beach | Strata or community corporation details needed |
| Industrial or warehouse | Wingfield, Regency Park, Lonsdale, Edinburgh | Full valuation likely |
| Retail or office | Rundle Street, The Parade, Prospect Road | Lease details reviewed |
| Vineyard or rural land | Barossa, McLaren Vale, Clare, Adelaide Hills | Full specialist valuation; allow extra time |
Example scenario: a McLaren Vale winemaker
Example scenario (generic, for illustration). Anna runs a family winery in McLaren Vale. A new export distributor has placed a large order, but she needs to pay for bottling, packaging and freight before the distributor pays on 90-day terms. At the same time, a director penalty notice has arrived for unpaid PAYG withholding from a tough season. She owns a rental house in Christies Beach outright. A caveat loan on the rental pays the PAYG inside the 21-day window and funds the export order. Her exit is the distributor’s payment, then selling or refinancing the house. With documents complete, 24–48 hours is realistic, and the vineyard itself doesn’t need to be offered.
Thinking about how the loan gets repaid is the most important part of any short-term loan. Our guide to exit strategies shows what lenders want to see.
Where we lend in South Australia
Adelaide CBD and all metropolitan suburbs, the Adelaide Hills, Barossa, Clare Valley, McLaren Vale and Fleurieu Peninsula, the Riverland, the Limestone Coast and Port Lincoln, subject to valuation.
Your next move
Apply now. It takes about 60 seconds and doesn’t touch your credit score. Or ring (02) 7208 8220 and ask for a lending specialist to call you back.
Questions we get asked
Can a vineyard or winery property secure an urgent loan?
Yes, business-purpose loans secured by vineyard and winery land are possible. They need a full valuation by a valuer who understands the region, so allow more time than for a suburban house and tell us early.
Are caveats in South Australia lodged electronically?
Yes, in most cases. The Registrar-General mandated electronic lodgement of caveats from 3 August 2020, with limited exemptions such as caveats over only part of a parcel that need a plan.
I supply a defence prime at Osborne and I'm waiting on payment. Can you help?
Often. Suppliers to large defence and infrastructure projects commonly wait on milestone payments. A cash flow loan on bank statements or a property-secured loan can fund the gap until the milestone is paid.
Do you need my financial statements?
Not for the first assessment on a property-secured loan. For unsecured lending, three to six months of business bank statements are the main document.
Can I use property in the Barossa or on the Fleurieu Peninsula?
Yes. Regional SA property can secure a loan, though it's more likely to need a full valuation than a metropolitan Adelaide property.
My bank said it needs three weeks. Can you move faster?
In many cases, yes. With complete documents and suitable property, 24–48 hours is possible. Timing still depends on the valuation type and how quickly every owner signs.